SnappPay says Iran’s BNPL market grew 33-fold in three years
SnappPay forecasts a 400 trillion-toman BNPL market in Iran as executives outline growth plans and economist Farhad Nili warns about declining real consumption.

Latest from Interview


SnappPay forecasts Iran’s buy now, pay later market will reach 400 trillion tomans in the Iranian year ending March 2027, after what its chief executive described as a 33-fold increase in market value over three years. The company presented the outlook at its “Note by note, in search of one voice” event, which brought hundreds of business leaders and retail industry participants to the Espinas Palace hotel.
The event reviewed six years of operations since SnappPay’s first credit transaction paid for a Snapp ride, when a monthly limit of 200,000 tomans covered seven or eight trips. Retail executives discussed how credit was changing customer behavior, while economist Farhad Nili warned that expanding credit in an inflationary economy does not necessarily mean consumers are buying more in real terms.
A path to BNPL without widespread credit cards
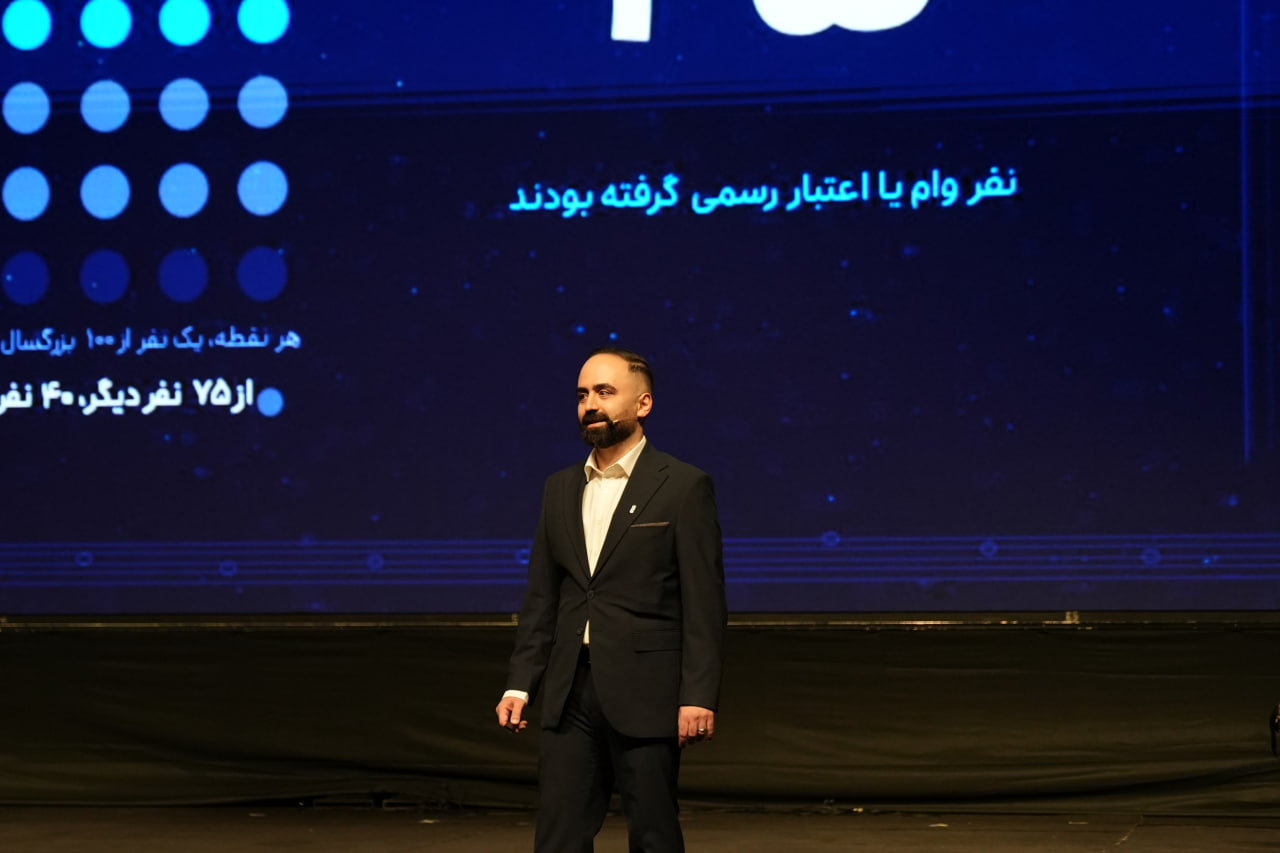
Majid Hesami, SnappPay’s founder and CEO and the event’s opening presenter, said 91 of every 100 Iranians had a bank account in the Iranian year 1399, which ran from March 2020 to March 2021. Smartphone penetration had reached 72%, but only 25 in every 100 people had access to loans or credit.
Of the remaining 75 people, 40 had borrowed from family or friends to meet their financial needs, he said. Hesami argued that the main gap was access to credit for a large part of the population, rather than access to bank accounts or digital tools.
Credit cards accounted for just 0.3 rials of every 100 rials transacted in Iran in that year, Hesami said, equivalent to 0.3% of transaction value. He compared that with global credit card shares of 21% for in-person purchases and 24% for online purchases in 2020.
He said that gap created an opening for buy now, pay later, or BNPL, a model offering credit without collateral, a guarantor or traditional loan procedures.
Unlike many other countries, Iran moved directly into developing BNPL without first establishing widespread credit card use, Hesami said.
From a 200,000-toman limit to a million daily orders
SnappPay was established in Tir 1399, or June–July 2020, and recorded its first credit purchase through Snapp’s ride service in Azar that year, or November–December 2020. The initial monthly credit limit was 200,000 tomans, enough for about seven or eight rides, Hesami said. The toman is Iran’s commonly used currency unit, equal to 10 rials.
Starting with transport was a strategic choice, he said. Frequent use and a high volume of transactions let the company study repayment behavior and develop a credit scoring model based on digital data.
In the Iranian year 1400, or March 2021–March 2022, the service expanded to food delivery platform SnappFood and grocery service SnappMarket. The monthly limit rose to 500,000 tomans, and registered credit users passed 1 million by Esfand, the final month of that year.
SnappPay introduced its four-installment product outside the Snapp group of services in Tir 1401, or June–July 2022. Initial limits ranged from 1 million to 5 million tomans, rising to 20 million tomans in the Iranian year 1402, or March 2023–March 2024.
Hesami said the company introduced card-based in-store shopping in 1402, but switched to a barcode model in Esfand that year, or February–March 2024, after a regulator intervened and the card-based method was halted.
Bank credit and a SnappPay wallet followed in the Iranian year 1403, or March 2024–March 2025. Hesami said the company recorded 354,000 four-installment orders in one day in Azar that year, or November–December 2024. That record reached 650,000 in Azar 1404, or November–December 2025.
In the Iranian year 1404, or March 2025–March 2026, SnappPay extended credit services to businesses operating on social media and added cashback and an investment wallet to its products.
19.1 million registered users and 175 million credit transactions
Presenting updated operating figures, Hesami said 45 million people were eligible for SnappPay credit and 19.1 million had registered with the company.
Monthly active users reached 4.7 million in Shahrivar 1405, or Aug. 23–Sept. 22, 2026. SnappPay recorded 175 million credit transactions over the preceding year, and its services were available in 804 cities, he said.
Daily credit orders had passed 1 million, while the network’s hourly record stood at 82,000 orders, Hesami said.
He said SnappPay was also working with more than 17,000 active merchants on social media.
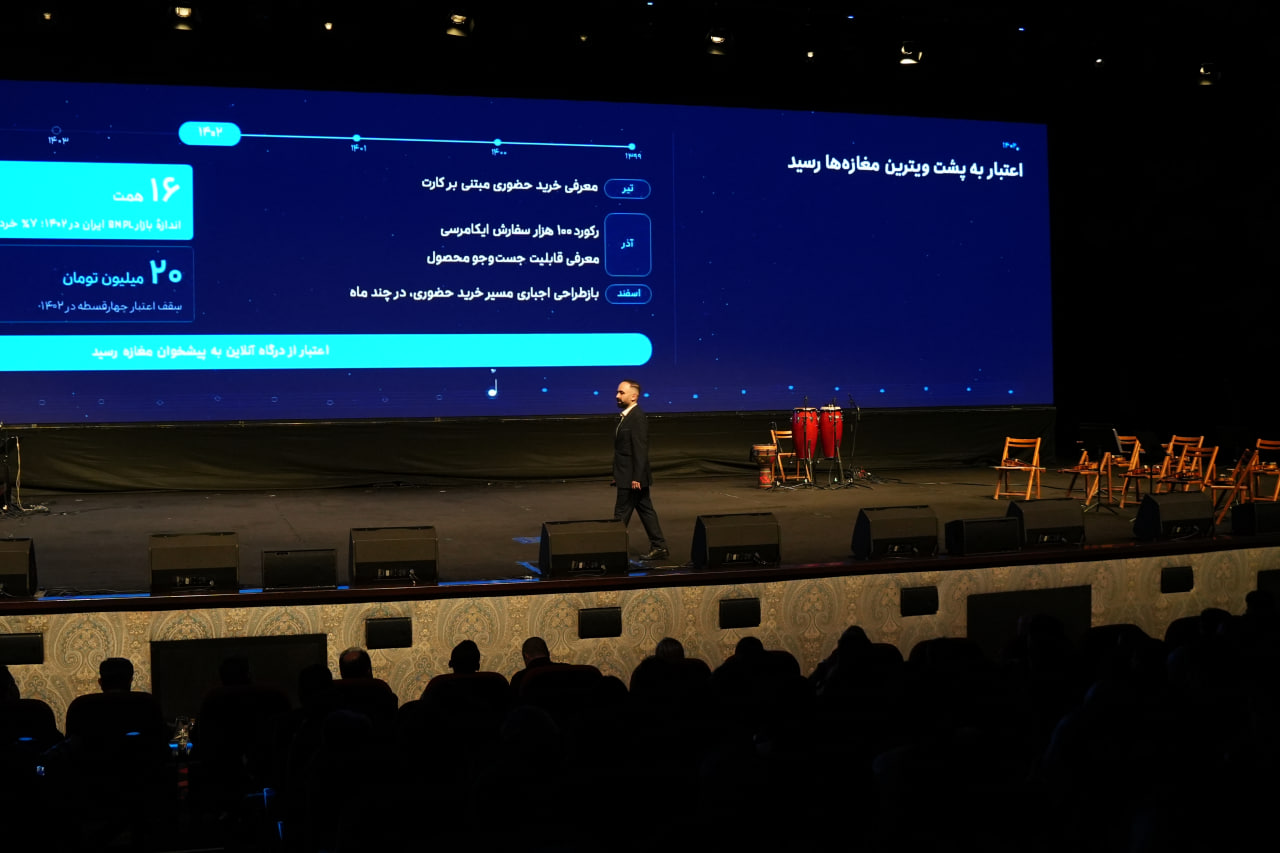
The figures presented showed that e-commerce orders never fell below 110,000 on any day in Shahrivar 1405.
Hesami said 95% of users had no credit score when they first used the service, largely because they had no history of borrowing from banks.
He put the installment repayment rate at 98.5% and said six-, nine- and 12-installment options would be added soon to support larger purchases.
A forecast of 28% of online retail
Hesami said Iran’s BNPL market grew from 4 trillion tomans in the Iranian year 1401, or March 2022–March 2023, to 16 trillion in 1402 and 132 trillion in 1404. The last of those years ran from March 2025 to March 2026.
Its share of online retail rose from 4% to 17% over the same period, he said.
Hesami said BNPL’s share of online retail in Iran in 2025 exceeded that in Britain and the United States, but remained below Sweden’s roughly 30%.
He forecast a market of 400 trillion tomans and a 28% share of online retail in the Iranian year 1405, which runs from March 21, 2026, to March 20, 2027.
In-store shopping was another major opportunity, Hesami said. According to the figures presented, credit purchases account for less than 0.5% of Iran’s in-store shopping market, compared with 1% to 4% in mature markets.
In dollar-denominated estimates presented by Hesami, Iran’s BNPL market would need to reach $6.3 billion by 2030 to achieve penetration comparable with Sweden. He put the estimate for the current Iranian year at about $1.1 billion.
He identified expansion into in-store purchases and social commerce, along with higher credit limits and longer repayment periods, as the drivers of future growth.
Hesami also discussed the possible development of six-, nine- and 12-installment products for larger purchases.
Finance chief says funding options remain limited
Ehsan Rahmani Nia, SnappPay’s chief financial officer and a board member, addressed the challenges of sustaining growth in consumer credit.
He said lasting growth depended on stable funding, financial discipline and risk management.
Leading companies internationally use credit lines, debt securities, short-term commercial paper and equity to fund operations, he said. Almost none of those instruments are widely available to Iranian credit fintech companies, according to Rahmani Nia.
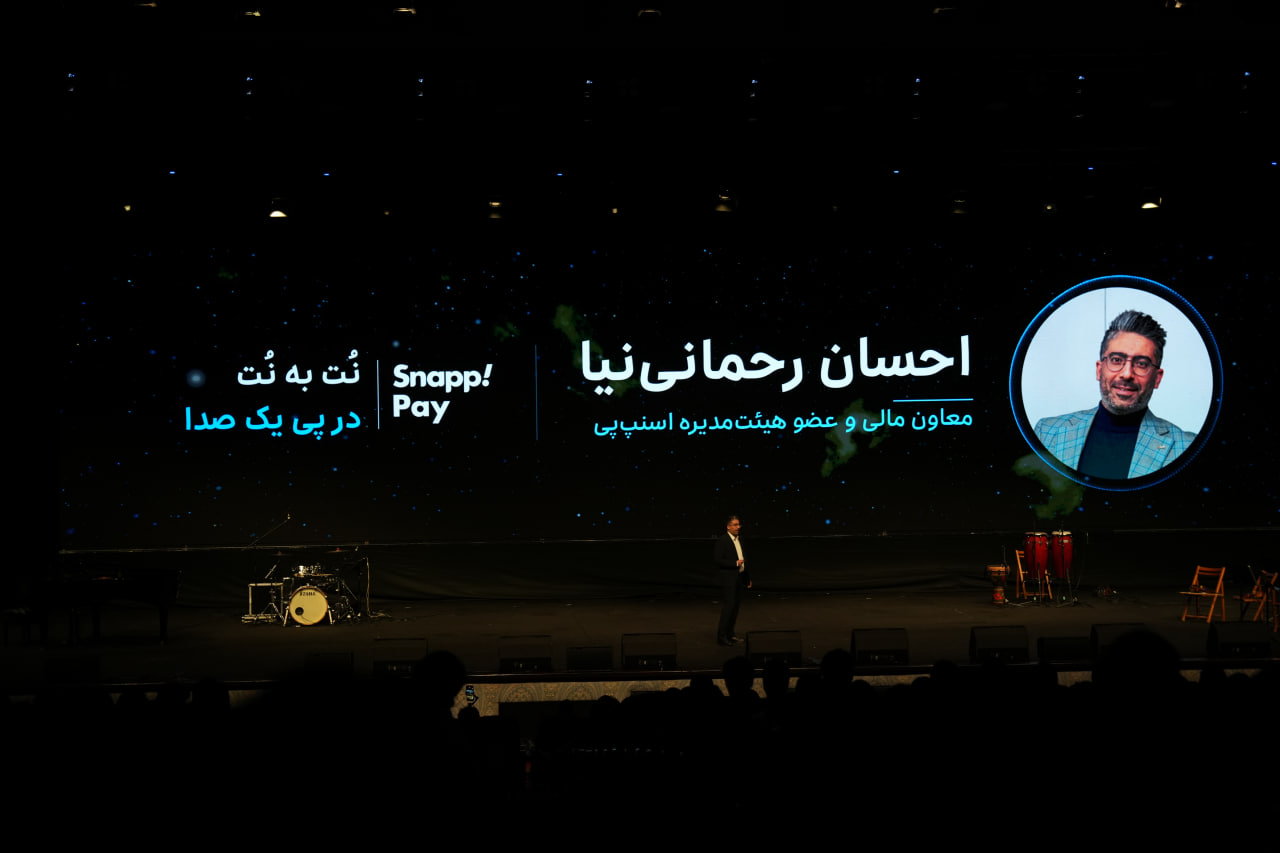
On financial discipline, Rahmani Nia said SnappPay had sought to manage its own risks rather than pass them to merchants or funders, even if that temporarily slowed growth.
Merchant settlements had been made on time, including during two wars, he said.
Rahmani Nia said that when SnappPay began offering unsecured credit, suitable credit scoring infrastructure did not exist and many users had no recorded banking credit history.
The company therefore built a scoring model using users’ digital activity across Snapp services, allowing credit decisions within seconds at the point of purchase, he said.
He said the model’s AUC score, a measure of its ability to distinguish lower-risk from higher-risk users, had improved from 68% to 81% over six years.
Rahmani Nia put the 90-day default rate below 2% and said 98.5% of installments had been repaid.
Monthly defaults rose during wartime before returning to their previous trend, he said. Across a 12-month period that included a 40-day war, 89% of repayments were made on time or early.
“Those 95 out of every 100 people were not bad customers; no one had given them credit,” Rahmani Nia said of users without a credit history.
Nili: Inflation brings future demand forward
Economist Farhad Nili examined how macroeconomic conditions affect BNPL growth.
He identified the lack of effective credit shopping options and the expansion of e-commerce as major reasons for the industry’s growth in Iran. Its future, however, needed to be assessed through several macroeconomic indicators together, he said.
Nili cited inflation of 90%, goods inflation of 123%, an economic contraction of 11% in the period through spring 1405, or spring 2026, a 4% fall in household consumption and annual liquidity growth of 56% through Khordad 1405, or May–June 2026.
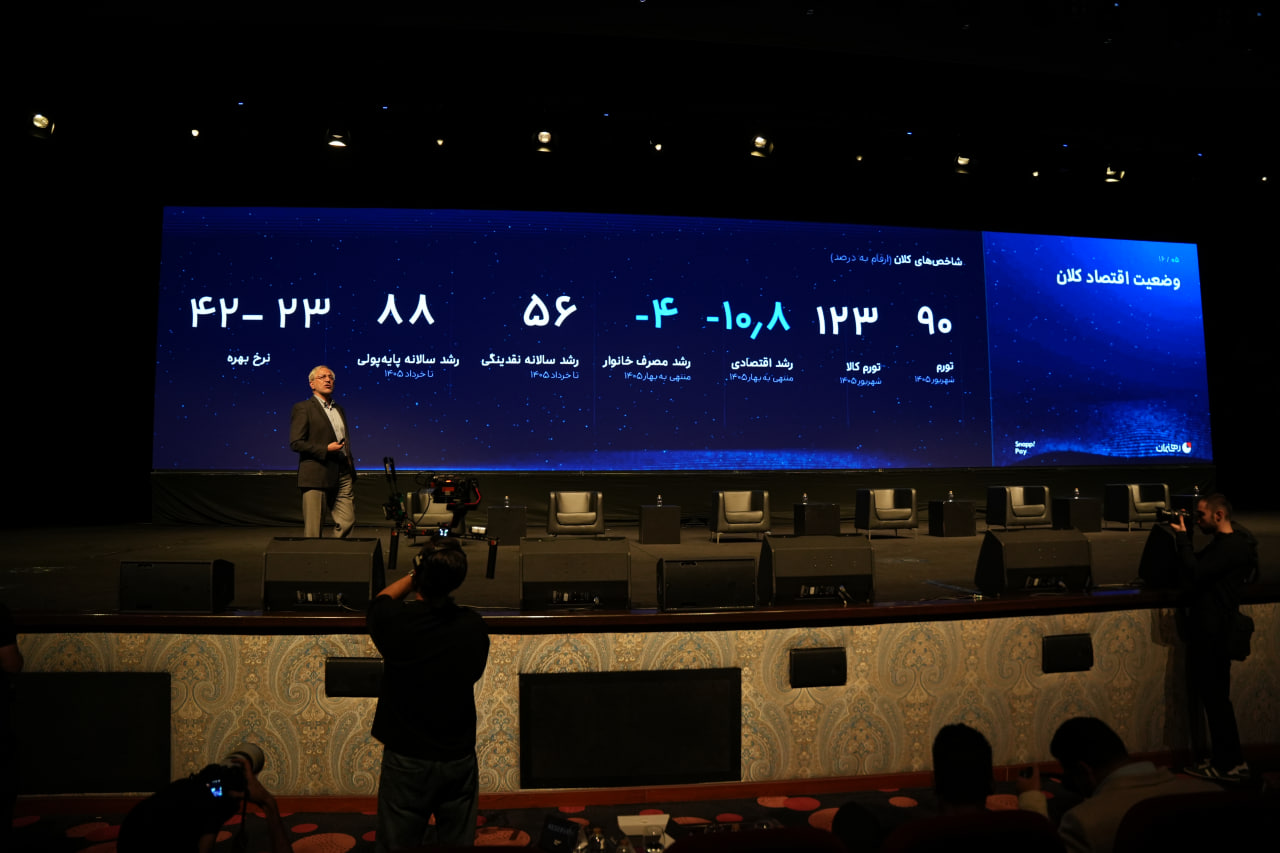
Those figures should not be analyzed separately, he said, because inflation, falling purchasing power and lower household consumption can together change consumer behavior.
One effect of inflation is to bring future demand into the present, Nili said. Borrowing can offer consumers an economic advantage when interest rates are below inflation.
But a larger share of household spending financed by credit does not necessarily mean real consumption is growing, he warned.
Declining real household incomes can increase the share of both credit purchases and necessities in household budgets, he said. Even if BNPL use expands, a deeper recession and lower overall consumption could reduce the credit shopping market’s value in real terms.
Nili called for mixed funding models in which banks and BNPL providers work more closely together instead of pursuing separate paths.
He said the industry also needed to move toward an integrated credit scoring system. BNPL providers should give greater attention to flexible settlement timing, sector-specific and scenario-based analysis, and lending based on customer profiles, he said.
Nili urged the main market participants to discuss cooperation on data and credit scoring. Competition between BNPL providers should not prevent the sharing of information needed to improve credit scoring infrastructure and develop the market, he said.
Different merchant models for small and large businesses
Ali Fadaei, SnappPay’s commercial vice president, discussed the merchant network and the company’s business partnerships in a presentation titled “Thousands of notes, one symphony.”
Merchants retain their independent identities while joining a larger network and using SnappPay’s infrastructure and platform services to expand, Fadaei said.
The aim was to give merchants access to SnappPay customers while helping them retain existing customers and broaden their own customer base, he said.
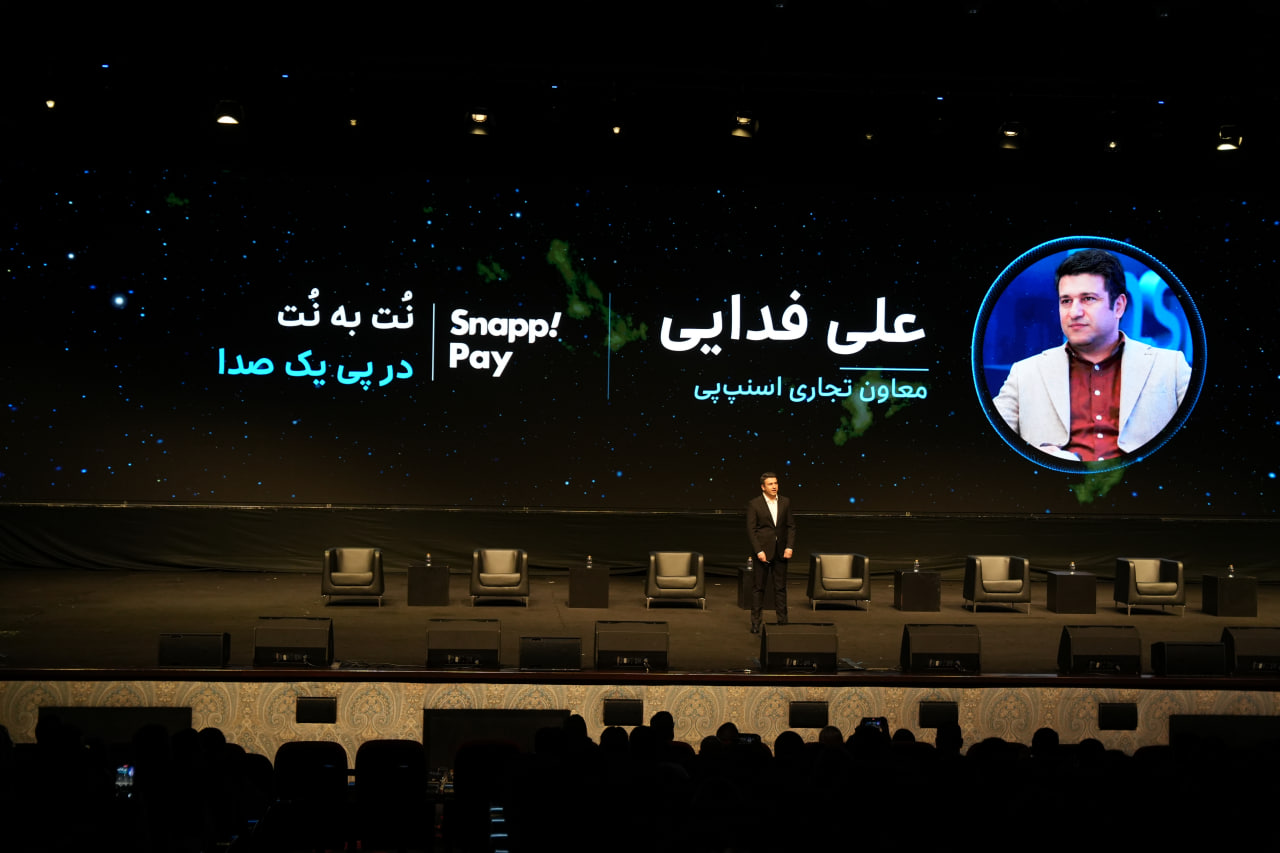
Fadaei said SnappPay had two partnership models, tailored to the size and needs of small and medium-sized businesses and larger companies.
For smaller businesses, SnappPay seeks to act as an “engine of growth,” he said. The model aims to increase customers’ purchasing power, send more traffic to merchants, support sales through campaigns and enable planning based on data.
Partnerships with larger businesses focus on creating new business opportunities, running joint campaigns and offering customers a distinct reason to choose their services, he said.
Repeat buyers account for 99% of orders
Mahdi Yeganeh, SnappPay’s marketing vice president, presented figures on purchasing behavior and referrals to merchants in a presentation titled “The harmony of notes.”
Yeganeh said users averaged 24 orders each. The company had recorded 42 million referrals to stores from product search and more than 2.4 million user referrals to its merchant network.
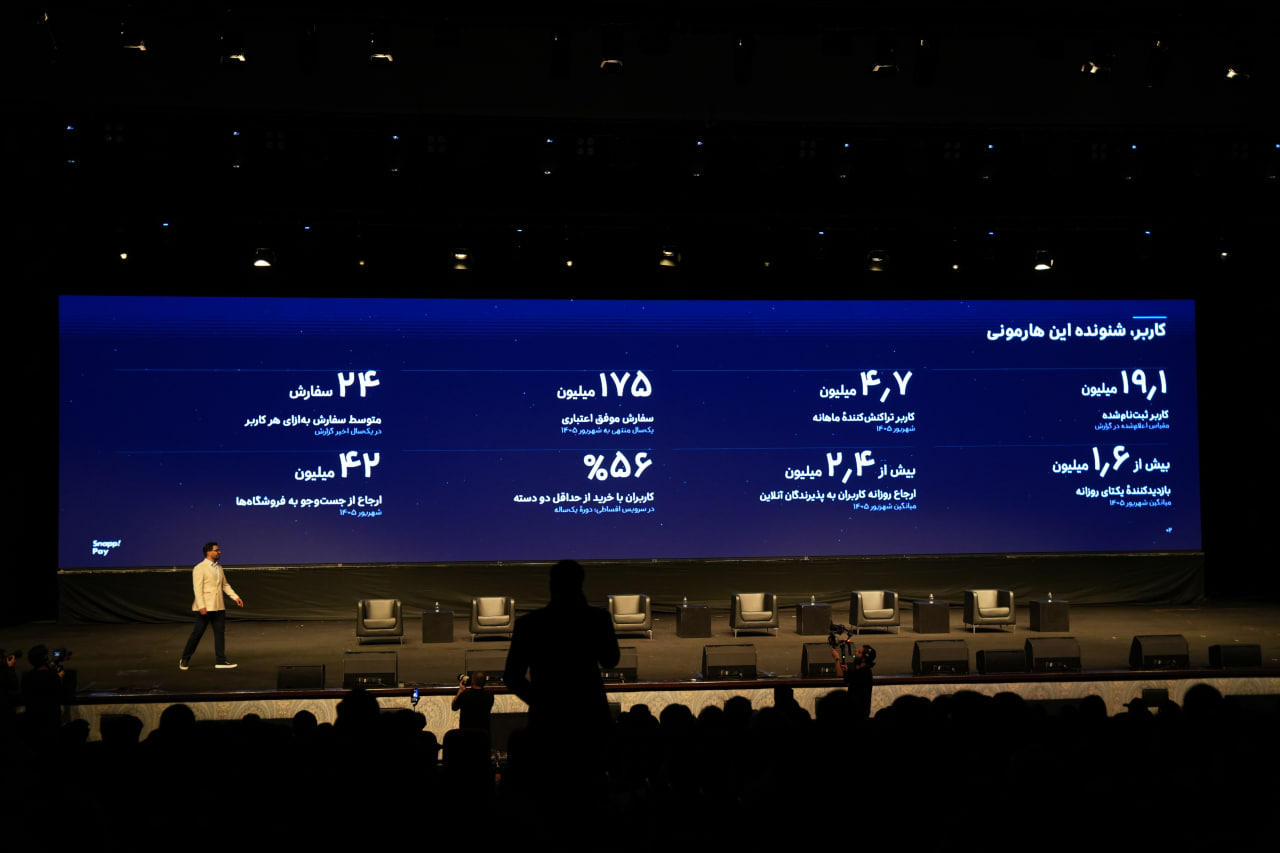
About 87% of all orders began on the SnappPay homepage, Yeganeh said, highlighting its role in users’ purchasing journeys.
He said 99% of orders recorded over the preceding year came from users who had made at least two purchases.
For users who joined the four-installment service in the Iranian year 1401, purchase value had risen about ninefold by their fourth year of membership, Yeganeh said. He described that increase as exceeding inflation over the period.