SnappFood reports 30% more orders from credit users in Iran
SnappFood reports more frequent but smaller credit orders as nine businesses describe SnappPay’s effects on sales, repeat purchasing and operations during wartime disruption.

Latest from Interview


SnappFood customers who pay through SnappPay place 30% more orders on average, but spend about 7% less per order than other users, the Iranian food delivery platform’s chairman said at a BNPL industry event.
The figures illustrate how buy now, pay later, or BNPL, can affect retailers differently. Beauty retailer Khanoumi reported higher repeat purchasing and larger baskets, while smaller businesses described gaining customers and keeping sales going during wartime disruption.
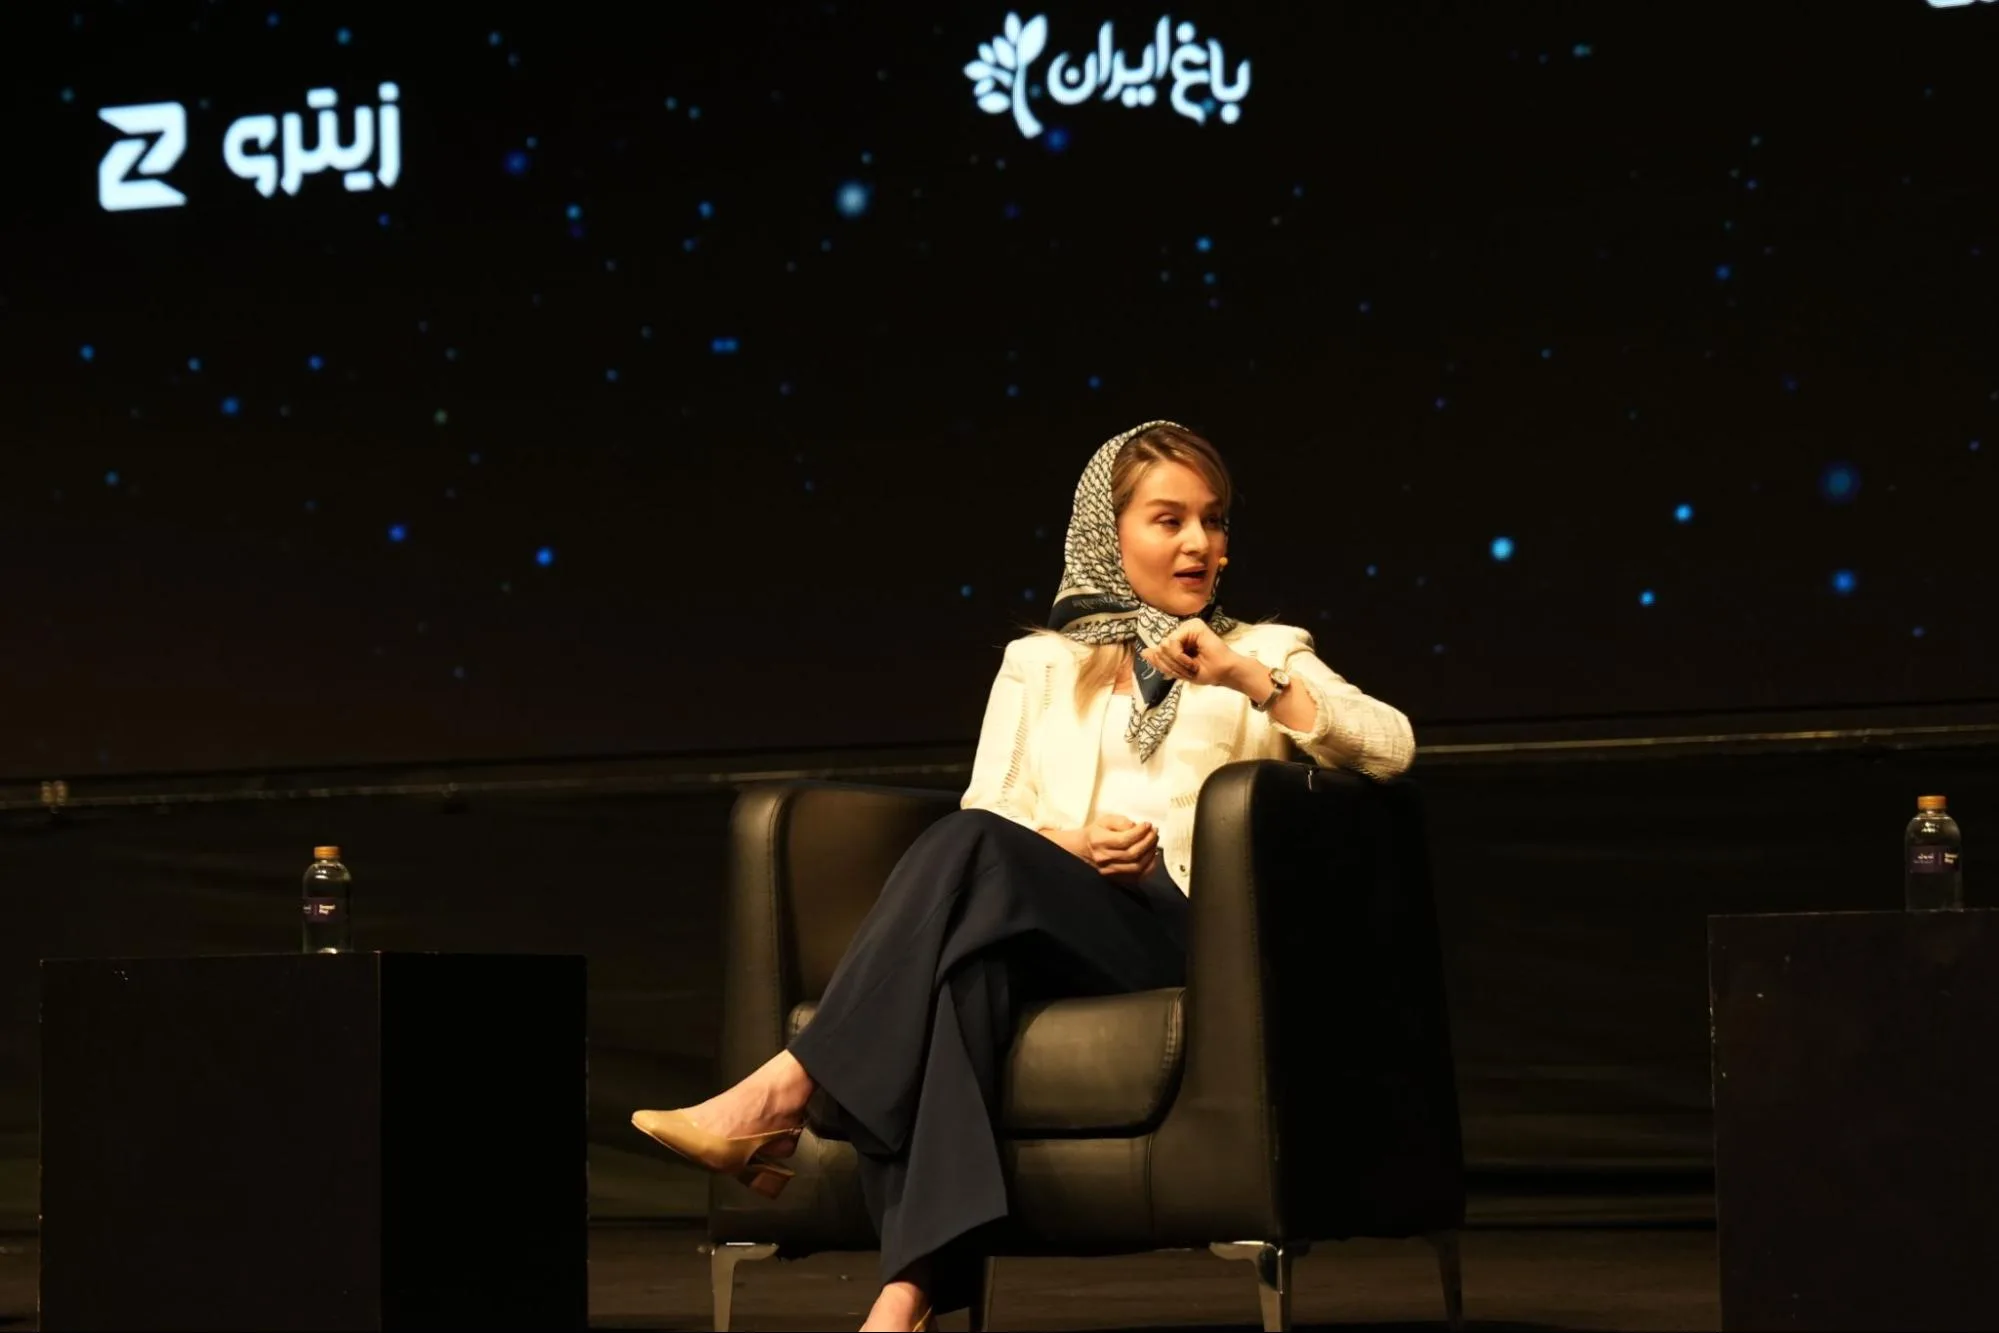
Executives from nine businesses spoke across two panels at SnappPay’s “Note by note, in search of one voice” event, held to mark the release of the company’s report on Iran’s BNPL industry. Digiato’s earlier coverage examines SnappPay’s market growth figures, expansion plans and an economist’s warning about falling real consumption.
The first panel, “Credit in the service of retail transformation,” was moderated by SnappPay CEO Majid Hesami. It brought together SnappFood Chairman Mehrad Abdolrazagh, Khanoumi CEO Masoud Shahmoradi, Charm Mashhad CEO Babak Mesri and Technolife CEO Hossein Heydar.
SnappFood: More orders, lower average spending
SnappFood began working with SnappPay six years ago and was the service’s second merchant partner, Abdolrazagh said. For a business whose customers make frequent purchases, reducing the effort involved in payment was an early priority. SnappFood had already found that users with money loaded into their wallets ordered more often.
In early research, about 40% of early adopters identified ease of payment as an important reason for using credit more, he said. Initial results showed purchase frequency rising by more than 30%, a pattern he said strengthened as the partnership continued.
More than 3 million monthly SnappFood orders across 170 cities are now paid for through SnappPay, Abdolrazagh said. Users of the payment method order 30% more often on average, although their average basket value is about 7% lower than that of other users.
Khanoumi: Repeat purchases and larger baskets
Khanoumi’s first meeting with SnappPay took place in the Iranian year ending March 2023, but the partnership took about 10 months to begin, Shahmoradi said. The beauty retailer initially wanted to assess the market’s response and potential risks. Looking at the experience of international businesses such as Sephora and Klarna also informed its decision.
The companies sought to share costs and risks at the start and used joint marketing campaigns to introduce customers to credit purchases, he said.
Shahmoradi said Khanoumi’s data showed a repeat-purchase rate 5% higher among credit customers than among cash-paying customers, along with 5% greater basket purchase volume. He also said that, in the Iranian year ending March 2026, the number of users Khanoumi encouraged to adopt credit purchasing rose by about 25% from the previous year.
Charm Mashhad: Extending installments to ordinary shoppers
Leather goods retailer Charm Mashhad had sought a way to offer credit to ordinary customers before partnering with SnappPay. It already sold in installments to employees of some government and semi-government organizations, but talks with banks failed to produce the arrangement it wanted, Mesri said.
The company began working with SnappPay in the Iranian year ending March 2023. A turning point came during Black Friday in 2023, when it reached the sales target for a four-day campaign by 6 a.m. on the first day, Mesri said.
That experience prompted the retailer to expand the partnership. Describing its credit business, Mesri put SnappPay’s share at more than 40% after about a year and a half.
Technolife: Credit limits meet expensive products
Electronics retailer Technolife faces a different constraint: expensive goods and narrow seller margins. Heydar said the same model for expanding credit could not be applied equally to electronics, food and clothing.
Technolife had already launched its own credit service, Technopay, before working with SnappPay. It decided to offer customers more payment options in the Iranian year ending March 2025 as inflation affected the economy, he said.
One difficulty is the gap between a customer’s available credit and a product’s price. Credit becomes more useful for an expensive purchase when the amount available better matches its cost, Heydar said.
Smaller merchants: Campaigns and search visibility
The second panel, “From credit to growth: Businesses’ experience with SnappPay,” was moderated by Alireza Etezadi, who heads SnappPay’s in-store shopping business line. Its participants were Ibolak founder and CEO Aybolak Pagh, Bagh Iran CEO Saeed Hakimian, Enekas CEO Nima Niknegar, Zitro CEO Mohsen Fattahi and Automobi founder and CEO Hamed Heydarian.
Bagh Iran developed its business to shorten the route between agricultural producers and consumers. Hakimian said small farmers faced export restrictions and sales difficulties during the coronavirus pandemic. Some intermediaries bought their crops cheaply and delayed payment for months.
The company began working with SnappPay in spring 2023. Hakimian said sales rose by about 4,000% during a campaign that summer, putting its supply chain under pressure to meet demand.
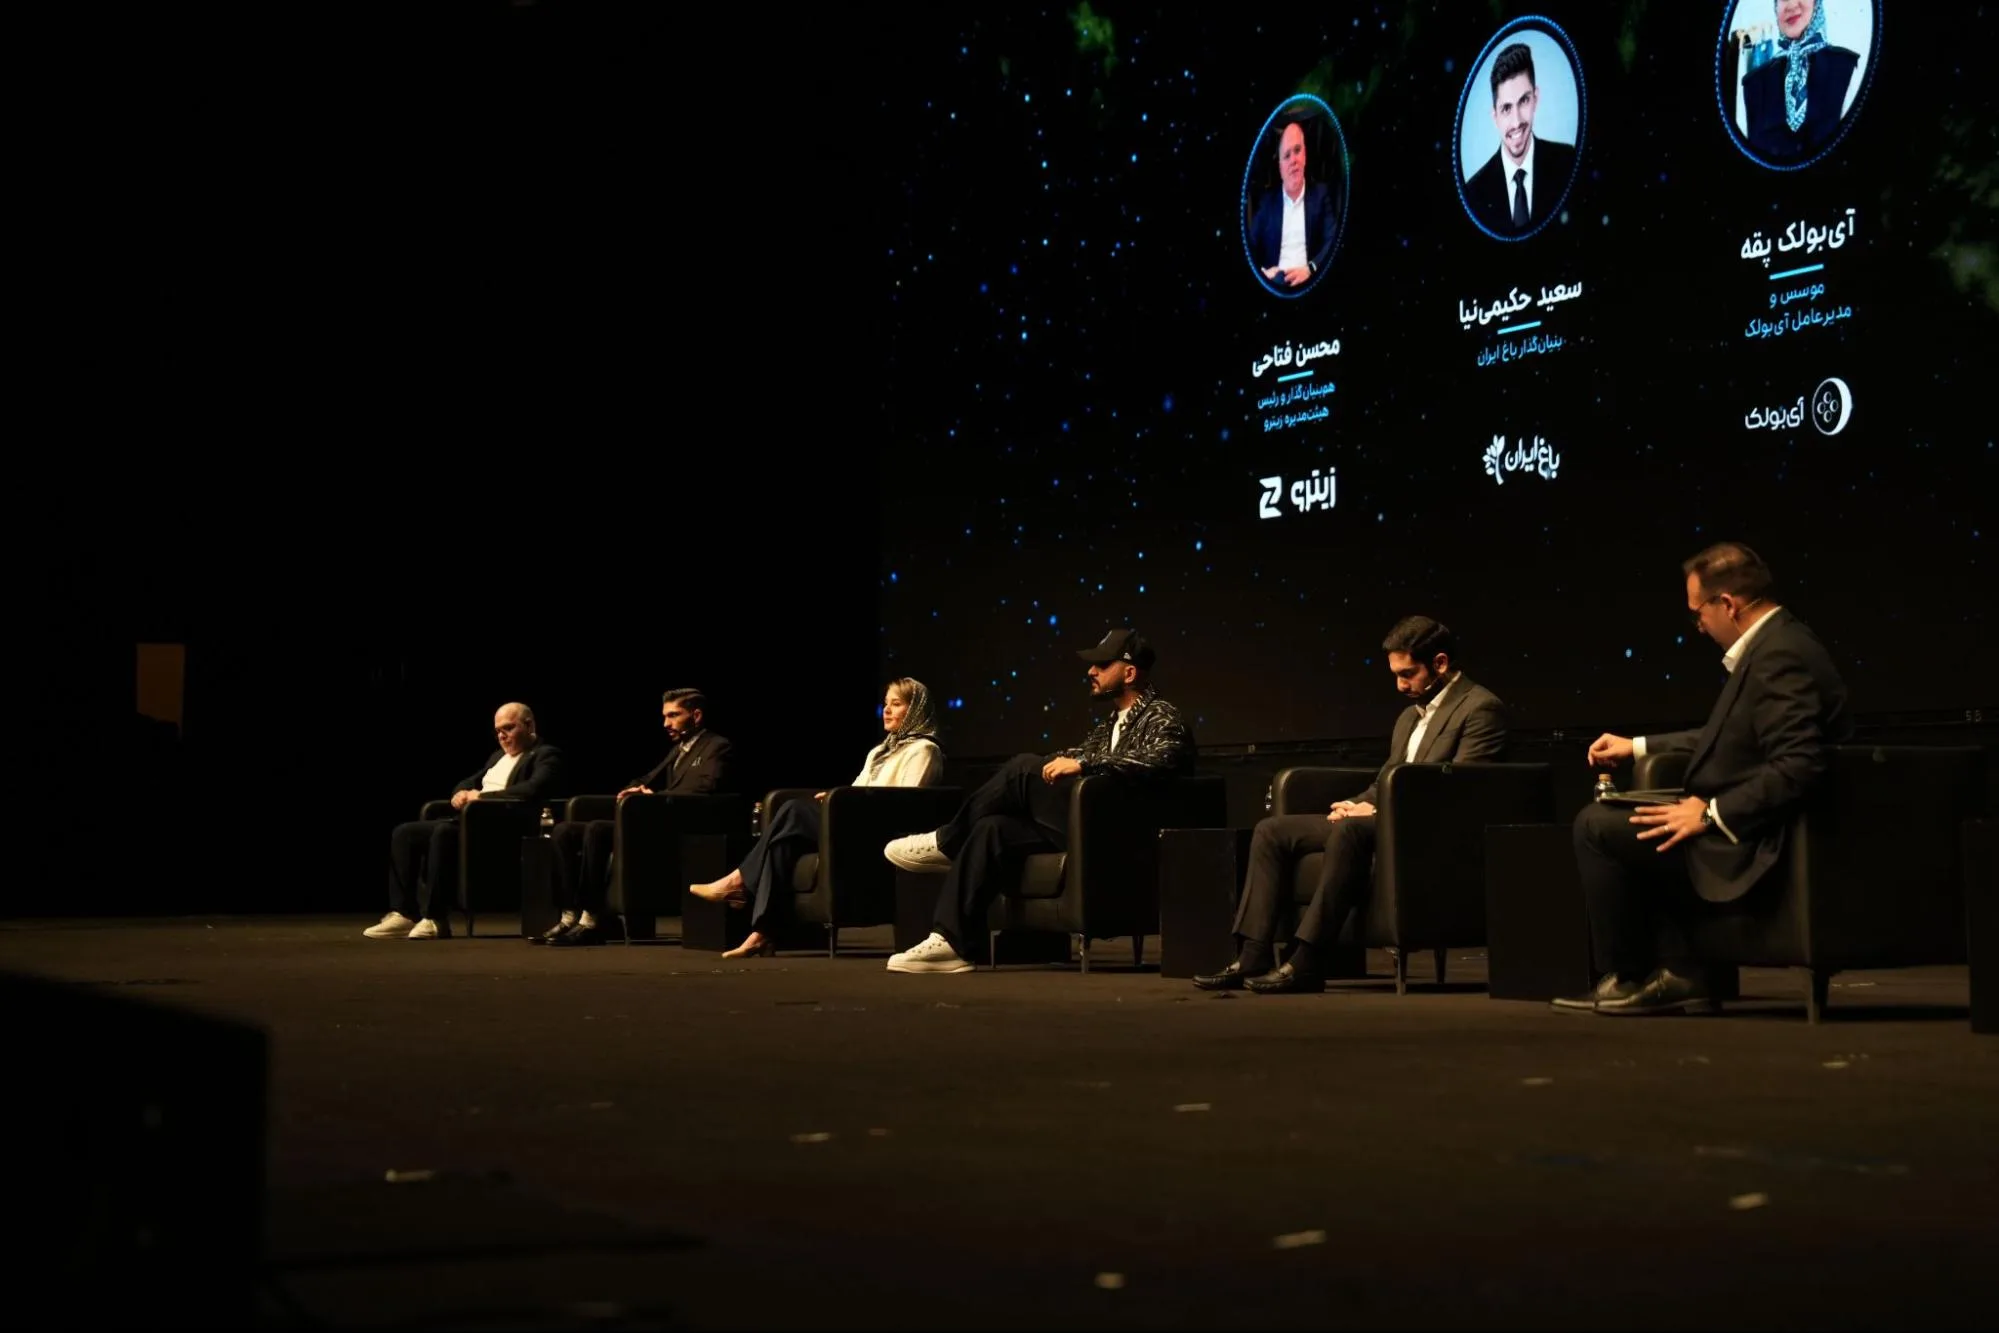
Higher sales allowed Bagh Iran to expand into other products and regions, from rice in Mazandaran province in northern Iran to spices in Sistan and Baluchestan in the southeast, he said.
Automobi, a specialist automotive spare-parts retailer, began its SnappPay partnership in the Iranian year ending March 2024. Heydarian said sales tripled after the store was added to SnappPay’s search section.
“I see SnappPay as an engine of growth for small, specialist businesses, stores that gain more opportunities to be seen and sell through this service,” Heydarian said.
He said spare-parts purchases cannot always wait: A customer may urgently need a component to repair a car without having enough money available to pay for it immediately. Credit can make it possible to obtain the part when it is needed, he said.
Keeping businesses running during wartime disruption
Enekas had relied on Instagram for a substantial part of its sales. Niknegar said it began working with SnappPay in February 2026, shortly before the outbreak of war.
He said credit purchases helped the business preserve some of its sales ahead of Nowruz, the Iranian New Year, and continue operating without layoffs. Enekas also launched a sales website and was planning to expand its physical branches, he said.
Niknegar argued that credit’s effects should also be assessed through continued operations, retained jobs and room for expansion, beyond sales figures alone.
Pagh described a similar experience at Ibolak. The business began working with SnappPay toward the end of the Iranian year ending March 2024. She said about 50% to 60% of customer purchases had been made on credit over the preceding year and a half.
The average number of items in customers’ baskets rose by about 35% to 45% during that period, Pagh said. She also credited installment purchasing with helping maintain sales and retain staff during the war.
One obstacle for retailers is a customer abandoning a purchase after choosing a product because they cannot afford to pay the entire amount at once, she said. Credit can remove part of that barrier and improve the likelihood of a completed purchase.
Zitro began working with SnappPay in May–June 2026. Fattahi said rising mobile phone prices and exchange-rate fluctuations had made purchases harder for some customers, while paying in stages made it easier for them to decide to buy.
Zitro uses more than 14 payment gateways, he said, identifying SnappPay’s ease of use as one reason customers chose the service. His account echoed the payment issue raised by SnappFood, while Technolife’s experience pointed to the separate question of whether the credit available is enough to cover a costly product.
The scope for further growth also depends on financing, credit risk management and merchants’ capacity to meet the demand generated.