Central bank defends gold and crypto credit ban in Iran
A central bank official defends the gold and crypto credit ban as business executives demand evidence of its impact and a timetable for lifting restrictions.

Latest from Interview


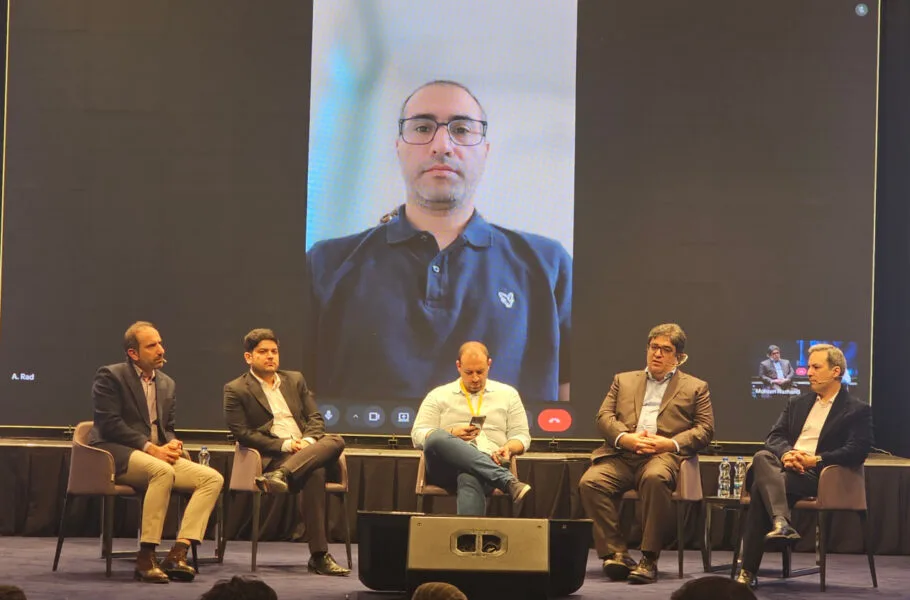
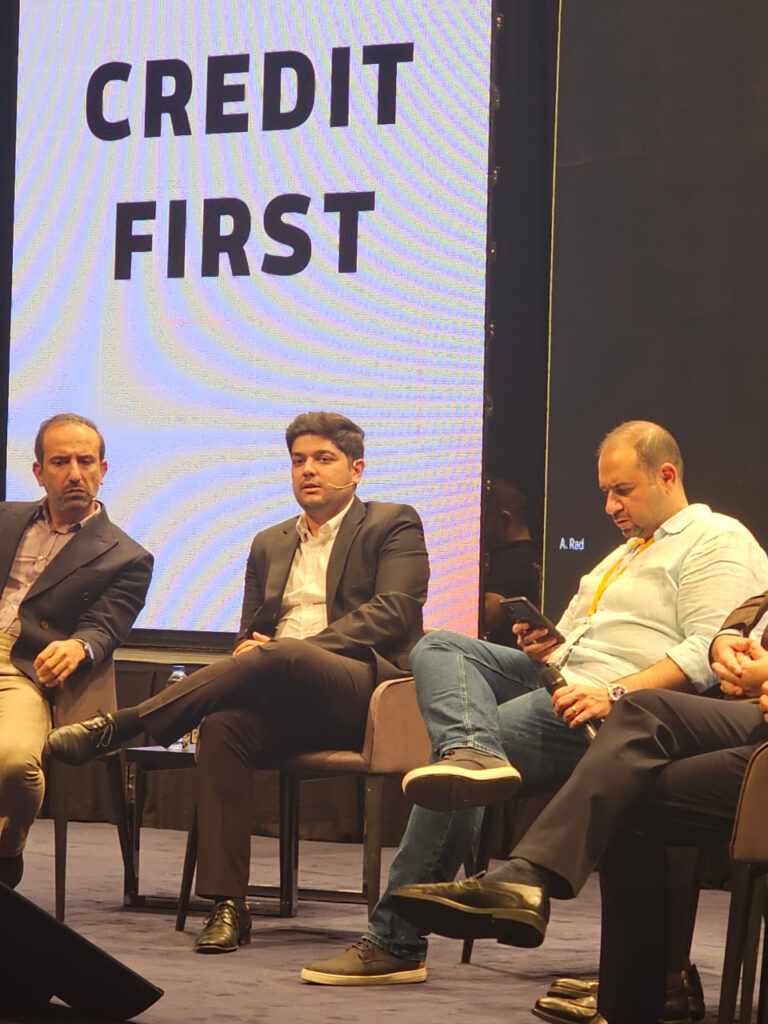
Iran’s central bank defended its ban on bank credit for gold and cryptocurrency purchases at a financial technology panel, as business representatives demanded evidence that the restrictions work and an explanation of when they would end.
The debate at the Finup event examined a directive circulated to banks in September that prohibits bank loans and credit for purchases of gold, foreign currency and cryptocurrencies. Speakers disagreed over whether restricting borrowers’ purchases addresses financial risks or merely treats the consequences of controlled interest rates.
For cryptocurrency exchanges and other businesses, the dispute also turns on a distinction between borrowing to buy an asset and using an asset already held as collateral. Executives argued that the two arrangements require different rules.
Central bank cites inflation expectations
Mohammad Reza Mani-Yekta, the central bank’s director general for payment systems supervision, said the decision should be judged against the economic and political circumstances in which it was made.
He cited postwar conditions and inflation expectations, saying policymakers sought to manage heightened sentiment in the stock and foreign exchange markets. Bank financing of gold transactions could also aggravate existing challenges in credit regulation, he said.
Mani-Yekta put monthly payments across the country at about 4,400 trillion tomans, including around 1,200 trillion tomans in e-commerce. Platforms trading melted gold account for about 25 trillion tomans in monthly turnover, he said. These are figures he cited for the broader payments market and gold platforms, rather than a measure of credit-funded gold purchases.
When another speaker proposed using interest rates instead of restrictions, he again invoked the country’s exceptional circumstances, responding: “Perhaps you have forgotten that we are at war.”
Who bears the risk of lending?
Nasser Hakimi, a former central bank deputy for new technologies, questioned whether credit for gold purchases met prudential requirements. Sellers’ capital and their ability to absorb defaults needed scrutiny, he said, so the risk would not fall on banks.
Hakimi also cited limited foreign exchange resources, asking whether the market could meet the additional demand generated by lending. Conditions that might be acceptable in normal times required a different assessment when resources were constrained, he argued.
He said lending at artificially suppressed interest rates transfers resources from depositors to people who can obtain loans, allowing those borrowers to buy gold on favorable terms. In his view, that preferential access reflects a wider problem across the economy.
Hakimi distinguished freedom to use one’s own assets from the use of borrowed funds. He called for closer supervision of banks’ asset composition, but described the directive as a superficial response to a deeper problem: loans that create such advantages should not be extended in the first place, he said.
Buying an asset or borrowing against it
Bardia Ahmadnia, board chairman of cryptocurrency exchange Wallex, said regulation should distinguish installment purchases of gold or cryptoassets from lending secured against those assets.
He argued that secured lending can be more defensible than many bank loans because the collateral is identifiable and can be used to cover a default.
Ahmadnia linked the appeal of borrowing at 23% to the gap between interest rates and inflation. Policymakers should examine why such borrowing makes economic sense for customers, rather than directing criticism only at gold purchases, he said.
He also questioned how effectively banks could control the use of loans issued with a guarantor but without collateral.
Ahmadnia said he would use interest rates to manage the market if he were in the central bank’s position. He called on the bank to publish the indicators behind its decisions and the results of its policies, arguing that those assessments should rest on evidence rather than intuition.
Businesses ask for an exit timetable
Amirhossein Rad, board chairman of cryptocurrency exchange Nobitex, opposed restrictions on how customers spend their loans. He argued that regulators and the state should not decide how borrowers use the money.
Rad said people were trying to preserve the value of their assets amid inflation. He likened the rial to a hot ball that everyone wants to pass on, questioning restrictions on the options available to people facing a loss of purchasing power.
While acknowledging the exceptional circumstances behind the decision, he said the burden should not be shifted onto middle- and lower-income groups. The authorities should explain when the restrictions would be removed and disclose their results, he said.
Referring to a SnappPay report on the size of the consumer credit market, Rad questioned whether the likely share used for gold purchases was large enough to have a broad effect on gold and foreign exchange markets. He called for documented explanations accompanying restrictive decisions, including the conditions for ending them and an assessment of whether they had worked.
Disagreement over controlled interest rates
Mojtaba Ghasemi, secretary of the Deregulation Board, argued that restrictions on economic freedom should be exceptional and require a convincing justification.
He described the directive as part of a wider system of administrative controls intended to steer bank credit. If banks were free to assess risk and reflect it in interest rates, he argued, the directive would be unnecessary. Administered rates instead create preferential benefits, he said.
Restrictions alone would not redirect money toward production if productive activity remained unattractive, Ghasemi added. Funds would still find their way into markets offering higher returns.
He said the command-and-control approach turns the central bank from a regulator into an intervening actor. Separately, he urged banks to avoid owning and running nonbank businesses.